
How to Build Lasting Business Value (Even If You're Years From Selling)
Key takeaways
- Lasting value is built over years, not in the months before a sale. The earlier you start, the more it accumulates.
- Value you build now gives you options later: sell, pass it on, or keep a stronger business, your choice.
- The levers that matter most take time: owner-independence, a leadership team, predictable revenue, and durable market position.
- Treat value as a standing part of your strategy, reviewed every year, not a project you start when you decide to leave.
Most owners think about the worth of their business only when an exit comes into view. By then the easy gains are gone. The value of a business is built slowly, through the choices you make years before anyone puts a price on it, and the owners who end up with the most to show for their work started building long before they needed to.
The stakes are higher than they look. Most businesses that go to market never sell, especially smaller ones, and even a majority of owners who do sell regret it within a year. I unpack the reasons in a companion guide, Why Most Businesses Don't Sell. The thread running through all of them is the same: the businesses that sell well are the ones that built durable value early, and this guide is about how to build it.
I am a business growth consultant and a certified exit planner, and I have built and sold my own businesses, and helped clients sell theirs. The lesson I keep seeing, and lived myself, is that value is a long game. The work that makes a business worth more is the same work that makes it stronger and easier to own today, so there is no reason to wait. This is written for the established middle-market owner who is years from any sale, or who is not sure they will sell at all, and wants the business to be worth more either way.
What does lasting business value mean?
Lasting value is worth that holds up no matter what you decide to do with the business. It is not a number on a single day. It is a durable asset that would attract a buyer, support a succession to family or management, or keep paying you well if you simply hold it.
A business can look valuable on paper and be fragile underneath, dependent on the founder, leaning on a few customers, with profit that wobbles. Lasting value is the opposite. It sits in things that endure: a business that runs without you, income you can rely on, a position in your market that is hard to dislodge, and a team that carries the company forward. Build those, and the worth is durable whoever ends up holding the business.
Why build value years before you need it
Three reasons make the long view worth taking.
It accumulates. Think of it like rungs on a ladder. The most impactful value drivers, a leadership team, recurring revenue, a brand people trust, take years to build and then keep paying off, and if a rung is missing, your business can never climb to the next level. Start early and they grow on top of each other. Start late and you are forcing in months what should have taken years.
It buys you options. A business with lasting value can be sold, handed to the next generation, sold to its managers, or kept as a strong income. A fragile business can do almost none of those well. Building value now means you get to choose later, on your terms, instead of taking whatever the moment allows.
It improves the business you own today. Every durable value driver also makes the business less stressful and less dependent on you right now. You do not have to sell to enjoy the return on this work. You get a better business to run in the meantime, and a more valuable one whenever you choose to move.
What steps should I take now to make my business more valuable in five years?
If you have a five-year horizon, you have time to build the value drivers that take the longest. Start these now, because they are the ones you cannot rush at the end.
Reduce how much the business depends on you. This is the single biggest driver of lasting value. Think of it as the first rung of the ladder: without it you cannot reach the others. Build a leadership team that decides without you, document how the work gets done, and move customer relationships to the company. My guide on building an owner-independent business covers this in depth.
Build income you can rely on. Convert one-off work into contracts, retainers, or repeat business so revenue is predictable, not chased every month. Predictable income is worth more to a buyer or a successor, and it makes the business steadier to run now.
Spread your customers and your risk. Reduce reliance on any single client, supplier, or person. The fewer single points of failure, the more durable the value.
Strengthen your position in the market. Sharpen what you are known for and to whom, and build a brand and reputation that a competitor cannot easily copy. Position, built over years, is one of the hardest things to take away, and easy to lose.
Build the team and the systems. These are key to commercial sustainability. Develop the people who will run the business, and write down the systems that let it grow without breaking. Both turn value that lives in your head into value that belongs to the business.
Get the financial discipline in early. Clean books, clear margins, and a habit of measuring what drives profit make every other decision better, and they take time to embed.
None of these is a quick fix, and that is the point. Begun now, they have five years to grow. Begun the year before you sell, most of them never get the chance.
How do I build lasting value for a future sale or succession?
The work above builds value that transfers, and that is what counts whether the business is sold or passed on. A buyer and a successor want the same thing: a business that keeps performing once you step back. I evaluate client businesses through this buyer or succession lens, and have the conversation that can mean telling you that your baby is ugly.
If a sale is the likely path, the value drivers translate directly into a higher price and better terms, and when you get closer my guide on increasing your business valuation covers the pre-sale mechanics in detail. If succession is more likely, whether to family or your management team, the same foundations apply, with one addition: the successor has to be ready. Developing the next leader, and giving them genuine responsibility years ahead, is part of building value that lasts beyond you. Either way, the goal is a business that does not need you, because that is what a buyer pays for and what a successor needs to inherit. I appreciate that for some this creates a fear of being cast aside and losing your identity.
Build for both, and you keep your options open. The business becomes sellable and inheritable at the same time, and you decide later which door to walk through.
Make value a standing part of your strategy
The owners who build the most value treat it as an ongoing strategy, not a one-time push. Initially every six months, step back and ask the value questions: how dependent is the business on me, how predictable is the income, how strong is our position, how ready is the team. Pick the weakest area and make it the focus, and use quarterly sprints to build momentum. Reinvest in the drivers that take longest. Track whether the business is becoming more durable, not just more profitable.
This is what a long-term business strategy looks like when value is part of it. Profit pays you now. Durable value is what you are building underneath, year after year, so that whenever you choose to sell, pass on, or simply step back, the business is worth what your years of work deserve.
Where to start
Pick the value driver that worries you most, the one where the business would struggle if you tested it, and make it this year's project. For most owners that is dependence on the founder, so start there. It takes the longest, pays back the most, and makes everything else easier.
This is the work I do with owners as a business growth consultant and certified exit planner: build the durable value that gives you options, whether you sell, pass the business on, or keep it. I have built and sold my own businesses and helped other owners build and transition something worth far more than the sum of its profits. If you want to make your business more valuable over the years ahead, that is what I help with.
FAQ
How do I build business value?
Build the drivers that last: reduce the business's dependence on you, make revenue predictable, spread your customers, strengthen your market position, and develop the team and systems. These take years to build and keep paying off, which is why starting early counts for more than any single tactic.
What steps should I take now to make my business more valuable in five years?
Begin with the slow-building drivers: owner-independence, a leadership team, recurring revenue, a wider customer base, a defensible market position, and clean financials. Pick one or two to focus on each year. A five-year horizon is long enough to build all of them if you start now.
How do I build lasting value for a future sale or succession?
Build a business that performs without you, because that is what both a buyer and a successor need. The value drivers are the same for either path. For a succession, add one thing: develop and empower the next leader years ahead, so the business can carry on once you step back.
How do I increase my business worth without planning to sell soon?
The same way you would for a sale, and the work pays off even if you never sell. Owner-independence, predictable income, a strong position, and a capable team make the business worth more and far better to own day to day. You get the return whether you exit or hold.
What is a long-term business strategy for value?
Treat value as a standing item, not a one-off project. Review the value drivers regularly, around every six months, pick the weakest and tackle it in quarterly sprints, reinvest in the drivers that take longest, and measure whether the business is getting more durable, not just more profitable. Profit pays you now, durable value is what you build underneath.
Adrian Bray is a business growth consultant, certified exit planner, chartered management accountant, and former international M&A advisor who has built and sold his own businesses. He helps middle-market owners grow, build a business that runs without them, and prepare for an exit on their own terms. Part consultant, part peer who has been in your shoes. To build value over the years ahead, get in touch.
Business Growth Consultant vs Fractional CFO: Which Do You Need?
Key takeaways
- A fractional CFO owns the financial engine: cash, forecasting, margins, reporting, and funding.
- A business growth consultant owns the growth and value agenda: strategy, revenue, leadership, systems, and exit readiness.
- The simplest test: if your problem is the numbers, hire a CFO. If your problem is what to do next and how to scale, hire a growth consultant.
- Many scaling businesses end up using both, in sequence or together, because they solve different problems and complement each other.
When a business gets big enough to need outside help but is not ready for a full executive team, owners face a practical question: who do I bring in, and to fix what. Two roles come up most, the fractional CFO and the business growth consultant. They are easy to confuse, because both are senior, both are part-time, and both promise to help you scale. They do different jobs.
I am a business growth consultant, a chartered management accountant, and a certified exit planner, and I have built and run my own businesses, so I have sat in the seat where you are now, weighing where to spend money I did not want to waste. I will give you the straight version: where a fractional CFO is the right hire, where a growth consultant is, and how to tell which problem you have. This is written for the established middle-market owner, the business with a team and genuine complexity, not a startup and not a one-person shop. Treat it as a plain business advisor comparison: what each role does, when each is the right hire, and how to choose.
What is a fractional CFO?
A fractional CFO is a senior finance leader who works with your business part-time. They own the financial engine room: cash flow and forecasting, margins and unit economics, management accounts and board reporting, financial controls, and the numbers behind raising money or doing a deal. They give you the financial visibility, across past, present, and future, and the rigor of a full-time CFO, without the full-time cost.
You feel the absence of a CFO as a fog around your numbers. You are not sure which products or clients make money, cash surprises you, the forecast is a guess, and when a bank or investor asks for figures you scramble. A fractional CFO clears that fog.
A fractional CFO is not a controller wearing a second hat, or the person doing your books with a fancier title.
What is a business growth consultant?
A business growth consultant works on the whole business, not just the finance function. They focus on the growth and value agenda: where the next phase of growth comes from, how to scale without it all running through you, building the leadership team and the systems, sharpening the go-to-market, and preparing the business to be more valuable and, when the time comes, sellable.
You feel the absence of a growth consultant as a ceiling. Revenue has flattened, the business depends on you, heavily or for everything, you are busy without getting bigger, and you can see where you want to go but not how to get the business there. A growth consultant works on that.
Business growth consultant vs fractional CFO: the core difference
The cleanest way to tell them apart is by the question each one answers.
A fractional CFO answers, "Are the numbers right, is the cash safe, and what do the figures tell us." Their work is financial depth: accuracy, control, forecasting, and funding. They make the financial engine reliable.
A business growth consultant answers, "Where do we grow next, and how do we build a business that scales and is worth more." Their work is breadth: strategy, revenue, people, systems, and value. They make the whole business bigger and less dependent on you.
Put simply, a CFO goes deep on the money and the flow of funds. A growth consultant goes wide on the business. One keeps the score, protects the cash, and keeps it flowing. The other changes the game and builds the value. Both care about profit, but they reach it from different directions.
Do I need a business consultant or a CFO to scale my company?
Start with the problem in front of you, not the title.
If your pain is financial, a fractional CFO is the right first hire. The signs: you cannot see which parts of the business make money, cash flow lurches and catches you out, you are raising capital or refinancing, your management accounts arrive late or not at all, or a buyer or investor needs numbers you cannot produce with confidence. Some growth initiatives even require bringing a capable fractional CFO forward sooner than planned.
If your pain is growth or dependence, a business growth consultant is the right call. The signs: revenue has plateaued, the business cannot run without you, you want to scale but the model will not stretch, you have no clear plan for the next phase, or you are getting the business ready to sell and need to lift its value.
A quick gut check. If you fixed only your numbers, would the business take off? If yes, you need the CFO. If your numbers are fine but the business is stuck or stuck on you, you need the growth consultant.
When a fractional CFO is the right hire
Bring in a fractional CFO when the financial function has outgrown your bookkeeper but does not yet justify a full-time CFO. They earn their fee fastest when you are scaling and cash is tight, when you are raising money or preparing for a transaction, when margins are a mystery, or when you need board-grade reporting you can trust. Good financial visibility also makes every other decision better, including the growth ones.
To be clear, that hire is not me. I am a growth consultant, not a CFO, and when finance is the gap, I will tell you to bring in a fractional or full-time CFO. My CMA background means I value the role and work well alongside it, but my lane is the growth and value side of the business.
When a business growth consultant is the right hire
Bring in a growth consultant when the constraint is the business itself, not the books. They are the right hire when growth has stalled and you need a credible plan, when the business depends on you and you want it to run without you, when you are scaling and need the leadership, systems, and go-to-market to match, or when you are building toward an exit and want to raise the value and reduce the risk a buyer sees. The work is as much about you stepping back as it is about the business stepping up.
Do you need both?
The short answer is yes, in sequence or side by side, because they solve different problems. A business scaling fast needs both a reliable financial engine and a clear growth agenda. They complement each other: the CFO gives the growth consultant trustworthy numbers to plan against, and the growth consultant gives the CFO a bigger, more durable business to account for, and a plan to forecast against. If budget forces a choice, pick the one that matches your sharpest pain now, and add the other when the first is handled.
For owners thinking about an eventual sale, the two roles map neatly onto exit preparation. The CFO makes the financials clean and defensible, and supports a buyer's confidence in how the business has been run. The growth consultant lifts the value and builds the owner-independence a buyer pays a premium for. My guides on building an owner-independent business and exit planning go deeper on that side of the work.
How to choose
Name your single biggest constraint, then match the hire to it. If the constraint lives in the numbers, start with the fractional CFO. If it lives in the strategy, the people, the dependence on you, or the plan to grow and exit, start with the growth consultant. Be candid about which one is holding you back, because hiring the wrong specialist solves a problem you did not have and leaves the true one in place.
This is the work I do with owners as a business growth consultant and certified exit planner: find the constraint that is capping your growth or your value, build the plan to remove it, and get the business to run and grow without you. I have built and sold my own businesses and helped other owners do the same. I have also experienced the impact of not bringing in a CFO or fractional CFO early enough. If you are weighing where to spend on outside help, I am happy to give you a straight read on which problem you have and what it needs.
FAQ
What is the difference between a business growth consultant and a fractional CFO?
A fractional CFO owns the financial engine: cash flow, forecasting, margins, reporting, and funding. A business growth consultant owns the growth and value agenda: strategy, revenue, leadership, systems, and exit readiness. A CFO goes deep on the money, a growth consultant goes wide on the whole business.
Do I need a business consultant or a CFO to scale my company?
Match the hire to your biggest problem. If you cannot see your numbers, cash is unpredictable, or you are raising money, start with a fractional CFO. If growth has stalled, the business depends on you, or you need a plan to scale, start with a growth consultant. Many scaling businesses use both.
Fractional CFO vs consultant: which is more cost-effective?
Neither is cheaper in the abstract, it depends on the problem. A fractional CFO pays back fastest when poor financial visibility is costing you money or blocking a raise. A growth consultant pays back fastest when stalled growth or owner dependence is capping the value of the whole business. The waste comes from hiring the one you do not need.
Can a fractional CFO help me grow the business?
A fractional CFO helps growth by making the numbers reliable, funding it, and showing which parts of the business are worth scaling. They are not the person who builds your go-to-market, leadership team, or operating model, that is the growth consultant's work. The two roles work best together.
Which do I need first if I am preparing to sell?
Both matter for an exit, in different ways. The fractional CFO makes the financials clean and defensible, which a buyer checks first. The growth consultant lifts the value and builds the owner-independence that earns a higher multiple. If the business leans heavily on you, start with the growth work, because it takes the longest.
Adrian Bray is a business growth consultant, certified exit planner, chartered management accountant, and former international M&A advisor who has built and sold his own businesses. He helps middle-market owners grow, build a business that runs without them, and prepare for an exit on their own terms. Part consultant, part peer who has been in your shoes. To get a straight read on what your business needs next, get in touch.
Why Your Business Stopped Growing (and How to Break the Plateau)
Key takeaways
- A plateau is not failure. It is the model that got you here running out of room, and breaking out takes a different move, not just more effort.
- Growth stalls for a short list of reasons: the owner is the ceiling, the model has maxed out, the team, systems, or structure cannot carry more, the leadership's skills have not kept pace, or focus has scattered.
- Breaking through starts by naming the one constraint that is capping your business, then aiming everything at it, instead of spreading effort across all of them.
- For most younger middle-market businesses the fastest unlock is removing the owner as the bottleneck, then concentrating on fewer, bigger bets.
Every business that grows eventually hits a plateau, and will hit others along its journey. Revenue flattens, profit retracts, the moves that used to work stop working, and you find yourself busier than ever with less to show for it. I have hit it in my own businesses, and I have helped plenty of owners climb out of it since. The plateau is not a verdict on you or the business. It is a sign that what got you here will not get you to the next stage, and that a different move is needed. This piece is about why growth stalls and how to break through.
What is a business growth plateau?
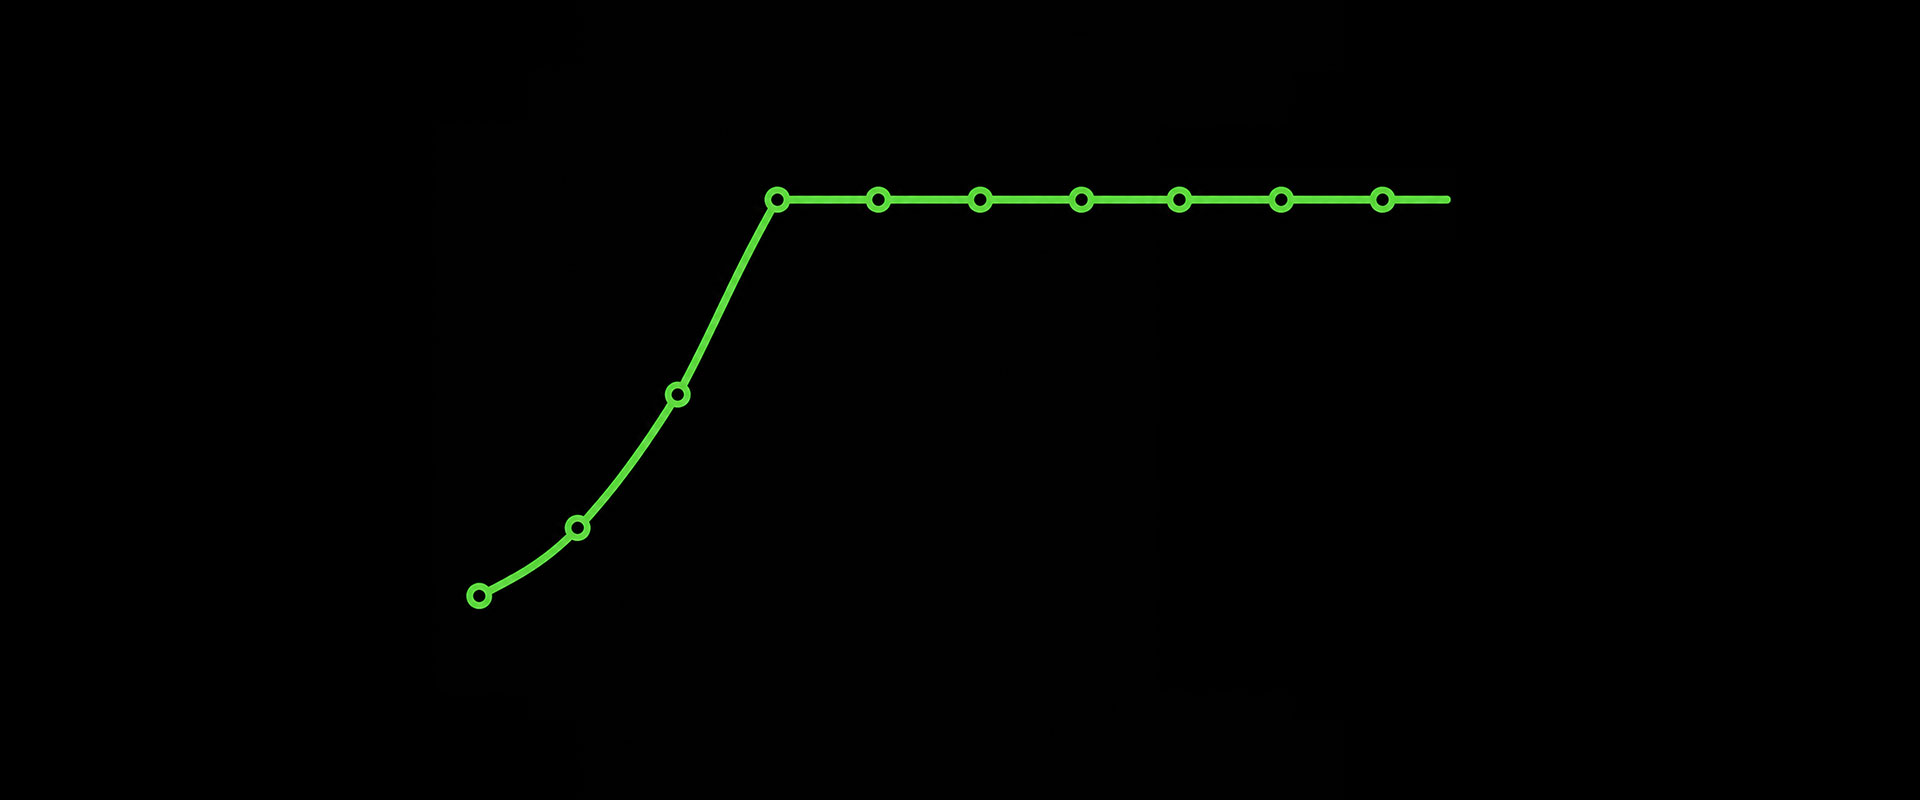
A business growth plateau is a stretch where revenue and profit stop climbing despite the same or greater effort. The graph goes flat. New work replaces lost work instead of adding to it. You are working harder to stand still, stress builds, and the levers that reliably produced growth a few years ago have quietly stopped responding.
A plateau is different from a decline, and it is different from a pause. It is the business bumping against a ceiling built into how it currently runs. Push against that ceiling with more hours and more hustle and you get exhausted, not bigger. Break the ceiling itself and growth resumes.
Where a stall sits in the business cycle
A plateau is a stage, not a dead end. Every business moves through a growth cycle, startup, incremental growth, accelerated growth, maturity, and then either renewal or decline, and the stall tends to arrive as the business matures and the moves that built it stop paying off. Reading it as a stage, not a personal failure, is what lets you act instead of stew. My article on timing your business cycle strategy sets out the three cycles that decide where you stand: the economic cycle, your industry cycle, and your own business growth cycle.
That distinction is worth drawing, because stalls come from two directions. External stalls come from the economic or industry cycle, a soft market or a maturing sector, and they call for a different response than internal ones. Internal stalls come from how the business is built and led, and those are the ones most within your control. This piece is about the internal stall and how to break it. If you are not yet sure whether you are stalling, my post on the hidden signs of a stalling business lays them out, and if the frustration has worn you down, my post on turning frustration back into passion is about getting your drive back.
Plateaus also come in different lengths, depending on the growth phase that preceded them and what you did to sustain the momentum. Internal plateaus have a variety of causes, and which one bites depends on the phase or stage the business is in within its own cycle. Common ones include an inability to invest, operational problems, weak infrastructure, and the skills and capabilities of your leadership team.
Why has my business stopped growing?
Growth rarely stalls for one dramatic reason. It stalls for one of a handful of quiet ones, and naming yours is the first step.
You are the ceiling. In most middle-market businesses the owner, and how they manage, is a key constraint. If sales, key relationships, pricing, hiring, and the hard decisions all run through you, the business can only grow to the size of your personal capacity, and you hit that wall long before the market does. My guide on building an owner-independent business covers how to remove yourself as the bottleneck.
The team and systems cannot carry more. Growth needs capacity. If your people are stretched, your processes live in your head or theirs, and there is no one ready to lead, the business physically cannot take on more without breaking.
You have outgrown your structure. Close to the two points above, but this one is about effectiveness, not raw capacity. The business has added people in each function, yet they are still run the old way. Money goes in, revenue barely moves, and costs climb sharply.
The model has maxed out. The same offer, sold to the same kind of customer, through the same channel, eventually saturates. What looks like a plateau is commonly a business that has fully worked its current market and has not built the next engine.
Focus has scattered. Success brings options, and options bring distraction. Many plateaued businesses are busy across too many products, customers, and side projects, spreading their best energy thin instead of concentrating it where it compounds.
Management capabilities have gone stale. As a business grows, so do the demands on management skills and capabilities. What it takes to run a business below $12 million is very different from what it takes above $20 million, and leadership that has not grown with the business becomes a cap on it.
You took your foot off. After years of hard driving, comfort and fatigue creep in. The business is doing fine, the pressure eased, and without quite deciding to, you stopped pushing for the next level.
Externally, the market moved. At times the ground changes, a new competitor, a change in what customers want, a channel that stops working, and the business keeps running the old playbook against a new game.
It is one or two of these, not all eight. The skill is being straight with yourself about which.
How do I break through a revenue plateau?
Breaking a plateau is not about working harder at what stopped working. It is a sequence.
Identify and name the true constraint and its source. Before you act, diagnose. What is the one thing that, if it changed, would unlock the most growth? For most owners it is their own involvement, or a lack of focus, but resist the urge to guess. Look at where work bottlenecks, where decisions wait, where you have been throwing people at a problem, and where your best people are stretched.
Get yourself out of the way. If you are the ceiling, this is the unlock. Build a leadership team that decides without you, document how the work gets done, and move customer relationships to the company. The business cannot grow past you until it can run without you. This takes an operational restructure, not just shifting your workload onto already stretched favorite team members.
Concentrate, do not scatter. Pick the two or three bets with the biggest upside and starve the rest of your attention. Plateaus break in this scenario when a business does fewer things with more force, not more things with less.
Build the capacity to grow, and make sure that capacity is effective. Put in the people, the systems, and the leadership the next stage needs before you need them, not after. Capacity built ahead of demand is what lets you say yes to growth instead of choking on it. But adding capacity without making its use more effective and efficient is a mistake I see again and again.
Find the next lever. When the current model is tapped out, growth comes from a new one: better pricing, a new customer segment, a new offer to existing customers, a new channel, or lifting retention so you stop refilling a leaky bucket. One well-chosen new lever restarts the climb. This is also the point to consider scaling, growing revenue faster than cost, not just adding more of the same; my article on the difference between growth and scaling covers when to make that move.
One example brings the sequence together. I worked with a legal firm that had grown its headcount tenfold in three years. They had added capacity but never properly addressed how the work was processed. Clients were frustrated by how long their cases took, the partners were disillusioned and fighting, and the staff came in like zombies, all working flat out but still following the way they had worked when the practice was a fraction of the size. Revenue had hit a ceiling while costs kept climbing.
We flipped the operating model and looked at the work like a factory floor: which step needed which level of skill, where the bottlenecks sat, where cases fell through the gaps, and where expensive senior people were doing junior work. Then we looked at who had the ability to step up and how fast they could be trained. The management team learned to run the business this way, alongside the traditional legal-delivery approach.
The result was more than 30% of capacity freed up compared with the old method. We moved some of that capacity into new roles, which released the revenue and profit that had been log-jammed. Clients grew happier, and a new generation of partners was able to step up, run the practice, and buy out the ones who felt trapped.
Put a plan on it, with clear responsibilities, success criteria, and accountability. A plateau rarely breaks on good intentions. Set a small number of clear targets, a rhythm to review them, and someone who holds you to the work when the day-to-day tries to pull you back.
Common plateau traps
The traps are as predictable as the causes. Working harder at the thing that already stopped working, because effort feels like progress. Chasing shiny new ideas instead of fixing the constraint that is holding you back. Cutting costs to protect profit and quietly starving the business of the growth you need. And blaming the market, which feels better than looking at the model or the mirror. Each one keeps you busy and keeps the ceiling exactly where it is.
Where to start
Name your one constraint this week. If the business would grow the moment you were less involved, start there. If your numbers are fine but nothing is moving, your problem is focus or a tapped-out model, and the fix is choosing fewer, bigger bets and building the next lever. Write down the single change that would unlock the most growth, and make it the work for the next ninety days.
This is the work I do with owners as a business growth consultant: find the true constraint behind a stalled business, remove it, and build the plan and the effective capacity to grow again. I have driven through, and stumbled inside, my own plateaus, and helped other owners break theirs. If your business has stopped growing and you want to know why and what to do about it, that is what I help with.
FAQ
Why has my business stopped growing?
One of a handful of reasons: the business depends too much on you or a key person, so it has grown to the limit of personal capacity; the model has saturated its current market; the team and systems cannot carry more; you have outgrown your structure, so added capacity is still run the old way; the leadership's skills have not kept pace with the size; focus has scattered; the market moved; or the drive that built the business has eased off. Naming which one is the first step to fixing it.
How do I break through a revenue plateau in my small business?
Diagnose the one constraint capping profitable growth, then aim everything at it. For most owners that means removing themselves as the bottleneck, concentrating on two or three bets instead of many, building the team and systems for the next stage, and adding a new growth lever like pricing, a new segment, or better retention. Put clear targets and accountability on it.
How do I overcome business stagnation?
Stop pushing harder on what stopped working and change the move instead. Find the ceiling built into how the business runs, most commonly the owner, an exhausted model, an outgrown structure, management skills that have not kept pace, or scattered focus, and break that specific thing. Stagnation ends when you fix the constraint, not when you add more effort.
What is a business growth plateau?
A stretch where revenue and profit stop climbing despite the same or greater effort, because the business has hit a ceiling built into how it currently runs. It is not a decline, and it is not solved by working harder. It breaks when you change what is capping growth.
Why is my business revenue stuck?
Stuck revenue almost always traces to a single constraint: you as the bottleneck, a saturated model, capacity that is run the old, inefficient way, or effort spread too thin. Find that one thing, aim your best energy at it, and the number starts moving again.
Adrian Bray is a business growth consultant, certified exit planner, chartered management accountant, and former international M&A advisor who has built and sold his own businesses. He helps middle-market owners grow, build a business that runs without them, and prepare for an exit on their own terms. Part consultant, part peer who has been in your shoes. To find what is capping your growth and build the plan to break through, get in touch.
Profitable Growth: How to Grow Without Taking On More Risk
Key takeaways
- Revenue growth and profitable growth are not the same thing. More sales can leave you poorer if each one costs more to win and deliver than it returns.
- Profitable growth means the business earns more than it spends to grow, so expansion funds itself instead of leaning on debt or your reserves.
- The safest growth is paced to what the business can absorb, in people, cash, and systems. Outrunning that limit is where the risk lives.
- You lower the risk of growth by protecting margin, funding from profit and cash where you can, and growing in steps you can stop and correct.
Many owners measure growth by the top line, but revenue is only half the story. As the old line goes, revenue is vanity and cash from profit is sanity. Profitable growth is growth where profit and cash rise with the revenue, so the business gets stronger as it gets bigger, not more stretched. The question I hear from careful owners is a good one: how do I grow without betting the business. This piece answers it, the difference between revenue growth and profitable growth, how to fund expansion without piling on risk or debt, and how to grow at a pace the business can carry.
Let's start with the word growth itself. It is used with so many assumed meanings that it is worth pinning down. I once asked a room of around 100 leaders what growth meant to them, and got 70 or so different definitions back. To one it was more revenue. To another, more profit, or a fatter margin on the same sales. Some meant more customers, or a bigger share of their market. Others meant more people, more locations, or a move into new territories. A few meant a more valuable business, worth more the day they choose to sell. And some meant something more personal: more freedom, less dependence on them, a business that finally ran without them in every decision. Each of those is a different destination, and each needs a different plan. The kind this piece is about is growth that leaves the business stronger and worth more, funded in a way that does not put it at risk.
I am a business growth consultant, a chartered management accountant, and a certified exit planner, and I have built and sold my own businesses. My accounting background means I have watched plenty of owners grow their revenue and shrink their bank balance in the same year. I went through it myself: I recall growing fast, the P&L looked great, and the cash flow nearly took us down. This is written for the established middle-market owner who wants the next stage of growth to leave the business more solid, not more fragile.
What is the difference between revenue growth and profitable growth?
Revenue growth is more sales. Profitable growth is more sales that leave more profit and more cash after everything it took to win and deliver them. The two usually move together, but not always. A business can grow its top line 30 percent, take on the extra staff, stock, space, and discounting to get there, and end the year with the same profit and less cash. That is revenue growth without profitable growth, and it is one of the most common ways a growing business gets into trouble. There are specific points in a company's growth where this gets amplified. In my own experience, and in what owners I work with keep confirming, the band between roughly $14 million and $19 million in revenue is where it bites hardest. It is the same leadership stretch I describe in breaking a growth plateau: the business has outgrown the way it was run, the rising top line starts to consume cash faster than the business can generate it, and many teams meet that stretch by trial and error instead of by design, which makes it worse.
Profitable growth asks a harder question than "did we sell more." It asks whether each new dollar of revenue brought a healthy margin with it, and whether the cash came in faster than it went out. When the answer is yes, growth compounds and funds itself. When it is no, growth eats cash, and the faster you grow the closer you get to the edge.
This is where venture-backed companies play a different game, and it helps to see why their playbook is not yours. Many VC-funded businesses chase revenue and market share ahead of profit on purpose, burning investor cash to win a winner-takes-most market before anyone else can. The bet is that dominance now pays off later, through profit after an IPO, a trade sale, or a further funding round that prices them on growth instead of earnings. It can work when the market is genuinely winner-takes-all and there is deep external capital to absorb years of losses. For the great majority of owner-run, middle-market businesses, neither of those conditions holds. You are funding growth from your own cash and your own balance sheet, there is no investor standing by to cover a shortfall, and running at a loss to buy share is a fast route to losing the business. Your version of winning is profitable growth, not growth at any cost.
Why chasing revenue can make you poorer
The classic trap is overtrading: growing sales faster than the business can fund them. New orders tie up cash in wages, stock, and work in progress long before the customer pays. Grow fast enough on thin margins and you can be profitable on paper and still run out of cash, which is how sound-looking businesses fail in a boom, not a bust.
I once launched a new country market for a privately held services business that was heading for an IPO. After getting it going I stepped away, and less than 24 months later I was asked back to help turn the group around and pull it out of bankruptcy administration. In the rush to look like a global player for an IPO on a European stock exchange, they had run out of cash and left it too late to secure funding. After I left they had opened four more geographic markets, launched too many service lines, and added too many support staff, all at once.
Growth also hides waste. When sales are climbing, sloppy pricing, creeping costs, and unprofitable customers are easy to miss. Take on volume at a discount to win it, and you can end up working far harder for the same profit, or less. More is not the goal. More that pays is.
How do I grow my business profitably without taking on too much risk?
The way to grow without betting the business is to grow deliberately, on the terms and the steps the business can carry. A few disciplines make the difference.
Know your numbers before you push. You cannot grow profitably if you cannot see which customers, products, and services make money after their true cost. A clear read on margin by line, and on how fast sales turn into cash, tells you what to grow and what to stop. This is the point where many owners bring in a fractional CFO or a growth consultant to get the visibility they have been missing.
Grow the profitable end, shrink the rest. Growth is a chance to improve the mix, not just enlarge it. Put your effort behind the customers and services with the best margins, and be willing to raise prices on, or let go of, the work that barely pays. A smaller, more profitable business grows into a bigger, more profitable one. A bigger, less profitable one just grows the problem.
Protect the margin as you scale. Watch that costs do not creep up faster than revenue, that discounts do not become the default, and that the cost of winning a customer stays well below what that customer is worth. Margin is the buffer that makes growth safe. Give it away and you remove your own margin for error, and your own ability to choose.
Grow in steps you can stop, at a rate you can manage. Experienced management teams know when to grow, and when to become efficient at a managed rate. The lowest-risk way to grow is in increments you can absorb and correct, not one leap you cannot walk back. Put another way, do not build a bathtub of capacity to hold a cupful of revenue, all in one go. Prove the next stage on a small scale, check the economics held, then commit more. My published guide on incremental versus exponential growth explains why pace is a choice, and the piece on the hidden pitfalls of accelerated growth covers what breaks when you grow faster than the business can take.
How to grow your business without debt
You do not have to fund growth with borrowing. The most durable growth is funded by the business itself: profit reinvested, and cash freed up from the way the business runs.
Fund it from profit first. Profitable growth generates the cash to pay for the next stage. When margins are healthy and you reinvest, growth compounds without a lender in the picture. This is slower than borrowing, and far safer, because the business is never carrying a repayment it has to meet whatever the market does.
Free the cash you already have. Before you borrow, look at the cash trapped inside the business: slow invoicing, long payment terms, overstocking, work sitting unbilled. Tightening the cash cycle can fund a surprising amount of growth from money that was already yours.
Use debt deliberately, not by default. There is a place for borrowing, to fund an asset that pays for itself, or to bridge a clear, short gap, but it should be a considered choice with a plan to repay, not the reflex that covers a business outrunning its own cash. Debt lifts both the return and the risk. In a soft market, the businesses that borrowed to grow are the ones that struggle first, which is why I have written separately about sustainable growth in a soft market.
Know when an equity investor makes sense. Sometimes the opportunity in front of you is genuine, time-limited, and bigger than your cash and profit can fund at the speed it needs. A land-grab market where being first counts, a product with a clear and closing window, or a step change that needs capital faster than the business can generate it, these are the conditions where bringing in an equity partner can be the right call. Equity is patient in a way debt is not: there is no repayment to meet in a downturn, and the right investor brings experience, networks, and discipline alongside the money. The trade is ownership and a share of control, so it only makes sense when the value of moving faster, with a partner who adds more than money, clearly outweighs the stake and the say you give up. Take equity for speed to market when the prize justifies it, not to prop up a business that is not yet profitable.
Grow at a pace the business can absorb
Every business has a speed limit set by its people, its cash, and its systems. Growth that respects that limit strengthens the business. Growth that ignores it strains everything at once: the team burns out, quality slips, cash runs short, and the culture frays. The skill is matching the pace of growth to what the business can carry, and building capacity ahead of demand so the limit keeps rising. It took me some tough experiences to learn these lessons.
Timing counts too. Growth is easier and cheaper to fund in some parts of the business and economic cycle than others. I have written about timing your growth to the business cycle, and the short version is that the best time to build capacity is before you need it, and the worst time to overreach is when the market is turning.
Business profitability tips that support growth
A handful of habits keep growth profitable as the business gets bigger.
- Price for value, not for volume. Better pricing drops almost straight to the bottom line, and is the fastest way to lift profit without lifting cost.
- Review margin by customer, market, and product, and act on it. Know your best and worst, and shift the mix toward the best.
- Watch cash as closely as profit. Invoice fast, collect faster, and keep a buffer so growth never leaves you exposed.
- Keep overhead lean as you grow. Add fixed cost only when the revenue to cover it is secure, not in anticipation of a good year.
- Reinvest with discipline. Put profit back into the drivers that compound, not into cost that only looks like progress.
Common mistakes
Confusing revenue with success, and celebrating a bigger top line while profit and cash stand still or fall. Buying growth with discounts, and training your market to expect the lower price for good. Funding growth with debt the business cannot service if the market softens. Growing faster than the cash cycle can support, so a profitable business runs out of money. And adding overhead and fixed cost ahead of secure revenue, so one slow quarter turns into a loss. Each one turns growth from a source of strength into a source of risk.
Where to start
Ask one question of your last year of growth: did profit and cash grow as fast as revenue. If revenue climbed and the other two did not, you have been growing the top line without growing the business, and the fix is margin and cash, not more sales. Start by finding your most and least profitable work, and shift your effort toward the former. Grow what pays, fund it from profit where you can, and pace it to what the business can absorb.
This is the work I do with owners as a business growth consultant and chartered management accountant: build the pricing, margin, and cash discipline that lets a business grow profitably and fund its own expansion, so growth leaves it stronger instead of stretched. I have grown my own businesses, and helped other owners grow theirs without betting the company. If you want to grow without taking on more risk than the business can carry, that is what I help with.
FAQ
What is the difference between revenue growth and profitable growth?
Revenue growth is more sales. Profitable growth is more sales that leave more profit and more cash after the cost of winning and delivering them. A business can grow its revenue and see profit and cash stand still, or fall, if the extra sales came with thin margins, heavy discounting, or a longer wait to get paid. Profitable growth is the kind that makes the business stronger, not just bigger.
How do I grow my business profitably without taking on too much risk?
Grow deliberately, on terms the business can carry. Know your margins by customer and product before you push, put your effort behind the profitable work and let go of the rest, protect the margin as you scale, and grow in steps you can stop and correct instead of one leap you cannot walk back. Fund it from profit and cash where you can, so growth never rests on a bet.
How can I grow my business without debt?
Fund growth from the business itself. Reinvest profit into the next stage, and free the cash already trapped in slow invoicing, long payment terms, and overstocking before you borrow. Use debt only as a deliberate choice for an asset that pays for itself or a clear short gap, with a plan to repay, not as the reflex that props up a business outrunning its own cash.
Can a business grow too fast?
Yes. Growing faster than the business can fund, staff, and systemize is one of the most common ways a profitable business gets into trouble. It ties up cash in orders you have not been paid for, burns out the team, and lets quality and margin slip. The safest pace is the one the business can absorb while building capacity ahead of demand.
What are the best business profitability tips for a growing business?
Price for value instead of volume, review margin by customer and product and shift the mix toward the best, watch cash as closely as profit, keep overhead lean until the revenue to cover it is secure, and reinvest profit into the drivers that compound. Small habits like these keep growth profitable as the business gets bigger.
Adrian Bray is a business growth consultant, certified exit planner, chartered management accountant, and former international M&A advisor who has built and sold his own businesses. He helps middle-market owners grow, build a business that runs without them, and prepare for an exit on their own terms. Part consultant, part peer who has been in your shoes. To grow profitably without taking on more risk, get in touch.
How to Scale a Small Business Without Losing Control
Key takeaways
- Scaling is not the same as growing. Growing adds revenue and cost together. Scaling grows revenue faster than the cost of producing it.
- You scale a small business by building the engine, a repeatable operating model, a leadership team, a predictable demand source, and the numbers to steer, before you pour on fuel.
- Scaling profitably means proving the unit economics first, then multiplying what works, not adding more of what barely pays.
- You keep control by letting go: control comes from systems, a capable team, and clear numbers, not from doing everything yourself.
Most owners want to grow, but what they need is to scale, and the two are not the same. Growing a small business tends to mean doing more of what you already do, with costs rising right alongside the revenue and will exceed them at critical points. Scaling means the business gets bigger without your costs, your stress, and your hours rising in lockstep. The fear that stops owners is losing control: more people, more customers, more moving parts, and the sense that the thing you built is getting away from you. This piece is about how to scale a small business the right way, profitably, and without losing your grip on it.
Growth versus scaling, and why the difference is worth understanding
Growth is more revenue. Scaling is more revenue without a matching rise in cost. A firm that doubles its clients by doubling its staff has grown. A firm that doubles its clients on a fraction more cost, because the work is systemized and the team is more productive, has scaled. My article on the difference between growth and scaling goes deeper, but the short version is this: scaling is what makes the business bigger than the sum of your hours, and it is the only kind of growth that makes the business more valuable and less dependent on you at the same time.
If your business has stalled, scaling is the way out, but only once the constraint that stalled it is fixed. My guide on breaking a growth plateau covers that diagnosis. This article assumes the diagnosis is done and the question is how to build for the next stage.
What it takes to scale a small business
You cannot scale chaos. Pour growth onto a business held together by your personal effort and you get a bigger, more fragile version of the same problem. Scaling starts by building the engine that can carry more weight.
Scaling a business from $1 million to $10 million is a job of systemization and operationalizing the business. Below $1 million, the business is mostly focused on doing the work and surviving. Above it, the work becomes building the machine that does the work.
A repeatable operating model. The work that makes the money has to be documented, systemized, and consistent, so it produces the same result whoever does it. Systems are what let output grow faster than headcount.
A leadership team that runs the day-to-day. You cannot scale a business that still routes every decision through you. Build the layer of leaders who own outcomes, and get yourself out of the operating seat. My guide on building an owner-independent business is the deepest treatment of this in the series.
A predictable way to win customers. Scaling needs demand you can turn up on purpose, not word of mouth you hope for. A repeatable and consistent sales and marketing engine, one you understand well enough to invest in, is what lets you grow the top line deliberately.
People ahead of demand. Hire and develop the right capability the next stage needs before you are drowning, not after. Scaling businesses build a bench in a disciplined way; scrambling ones are always one departure from a crisis.
Numbers you can steer by. A simple dashboard of the few measures that decide health, revenue, pipeline, margin, cash, and capacity, tells you whether scaling is working before the bank balance does.
How to scale a small business profitably
Bigger is not the goal. More profitable at a larger size is the goal. Scaling a business profitably comes down to a few disciplines.
Prove the unit economics first. Before you pour money into growth, know that each unit of work, each customer, each product, makes money after the true cost of delivering it. Scaling a model that loses a little on every sale just loses more, faster. Know your step changes, the points where the unit economics change as you grow.
Multiply what works, starve what does not. Scaling is not the time for a dozen experiments. Find the two or three things that are proven to be profitable and repeatable, and put your capital and attention there.
Protect the margin as you grow. Growth hides inefficiency. As you scale, watch that costs do not quietly creep up faster than revenue, that discounts do not become the norm, as your team chase revenue at all costs, and that the delivery model stays as lean and aligned as it was small. Understand your step costs, the fixed and semi-fixed costs you have to add to lift capacity, so a jump in volume does not quietly wreck the margin. My published guide on scaling without the hidden risks goes through the traps in detail.
How to scale without losing control
Here is the paradox at the heart of scaling: the more you try to keep control by holding on, the faster you lose it. A business that depends on you cannot grow past you, and the harder you cling, the more it strains. True control at scale comes from a different place.
Control comes from systems, not from your hands on everything. When the process is documented and consistent, you control the outcome without touching every task. Control comes from a capable team with clear decision rights, so you know who decides what and can trust them to. And control comes from the numbers, a dashboard and a review rhythm that let you see what is happening across a bigger business without being in every room.
Culture is the quiet part of control. As you add people, the values and standards that lived in your head have to become explicit, so the business behaves the way you would even when you are not there. Owners who scale well keep their hand on the strategy, the culture, and the numbers, and take it off the daily work. That is how you grow the business and keep it yours.
Small business growth strategies that scale
Not every growth tactic scales. The strongest small business growth strategies are the ones that add revenue without adding proportional cost.
Sell more to the customers you already have. Expanding what existing customers buy is the cheapest, most scalable growth there is, because the relationship and trust are already paid for.
Build recurring revenue. Contracts, retainers, and subscriptions turn one-off effort into income that compounds, and they make the business steadier and more valuable as it grows.
Productize what you do. Turning a bespoke service into a repeatable package or product lets you deliver it more consistently and at a lower cost each time.
Add a channel or a segment, once the core is solid. A new market or a new route to customers can restart the climb, but only after the base model is proven and systemized enough to carry it.
Use pricing as a lever. Better pricing drops almost entirely to the bottom line, which makes it one of the fastest ways to scale profit, not just revenue.
Common scaling mistakes
Scaling too early, before the model is proven, so you multiply a loss. Scaling the owner-dependent version of the business, so every new customer adds to the load on you. Chasing growth so hard that margin, culture, and quality quietly erode. And confusing being busy with scaling, adding activity instead of building the engine that lets output outpace effort. Each one turns scaling into a faster route to burnout instead of a bigger, better business.
Hiring a COO and dumping your workload on them. A common mistake I have seen is hiring a COO and offloading the tasks you do, without giving them the room to develop and build the platform that supports scaling. The COO becomes a black hole within eighteen months and quits within two years, and I get called in to fix the aftermath.
Treating documentation as a one-time job. Thinking that because you captured the work once, it is finished. It is not. As a business scales, roles get more specialist, processes and workflows have to adapt, and the client base itself changes and grows more sophisticated.
Building incrementally instead of from the vision. Most small businesses plan year after year, building on where they were, instead of tying the plan to where they are going and designing the build-out backward from that scale vision.
Where to start
Before you try to scale, ask one question: if you tripled the volume tomorrow, what would break first? The answer is where to build. For most small businesses it is either the owner as the bottleneck or a delivery model that only works by hand, so start by systemizing the core work and building the team to run it. Prove the economics, build the engine, then add fuel.
This is the work I do with owners as a business growth consultant: build the operating model, the team, and the numbers that let a business scale profitably and run without its founder, so growth makes the business stronger instead of more fragile. I have scaled my own businesses and helped other owners do it without losing control. If you want to grow without the business running you, that is what I help with.
FAQ
How do I scale a small business?
Build the engine before you add fuel: a documented, repeatable operating model, a leadership team that runs the day-to-day, a predictable way to win customers, people hired ahead of demand, and a simple dashboard to steer by. Then multiply what is proven to work, instead of adding more of everything.
What is the difference between growing and scaling a business?
Growing adds revenue and cost together, more clients by way of more staff. Scaling grows revenue faster than the cost of delivering it, because the work is systemized and the team is more productive. Scaling is the kind of growth that raises profit and value without raising your hours.
How do I scale my small business without losing control?
Control at scale comes from systems, a capable team with clear decision rights, and the numbers to steer by, not from doing everything yourself. Document the work, hand genuine ownership to your leaders, make the culture explicit, and keep your hand on strategy and the numbers while taking it off the daily tasks.
How do I scale a business profitably?
Prove the unit economics before you invest, so each customer and product makes money after its true cost. Then put your capital into the two or three things that are proven and repeatable, and protect the margin as you grow so costs do not creep up faster than revenue.
What are the best small business growth strategies to scale fast?
The ones that add revenue without adding matching cost: selling more to existing customers, building recurring revenue, productizing your service, sharpening pricing, and adding a new channel or segment once the core model is proven and systemized. Fast and durable both depend on scaling a model that already works.
Adrian Bray is a business growth consultant, certified exit planner, chartered management accountant, and former international M&A advisor who has built and sold his own businesses. He helps middle-market owners grow, build a business that runs without them, and prepare for an exit on their own terms. Part consultant, part peer who has been in your shoes. To scale your business without losing control, get in touch.
Is Hiring a Business Growth Consultant Worth It? A Straight Look
Key takeaways
- A growth consultant is worth it when the constraint on your business is strategy, focus, or you, not when you simply need more hands or a single specialist function.
- The simple test: would an outside expert who has built and sold businesses help you make better decisions, faster, than working it out alone.
- It is not worth it if you will not act on the advice, if your problem is purely financial (that is a CFO), or if you want someone to do the work instead of changing how the business runs.
- Judge a consultant on whether they have run businesses themselves, their track record, and the fit, not the polish of the pitch.
- The return shows up as clearer decisions, more of your time back, faster profitable growth, and a business that is more valuable, less stressful, and less dependent on you.
I am a business growth consultant, so read this with the obvious bias in mind. I am not going to pretend hiring one is always the right move, because it is not. What I can give you is the straight-up version, from someone who has been the owner writing the check and unsure it was worth it, and who later ran an international M&A advisory firm and saw which businesses had used good advisors and which had not. Here is when a growth consultant pays off, when it does not, and how to pick one who earns their fee.
What does a business growth consultant do?
It helps to start with the word itself, because "consultant" is one of the loosest titles in business. I know and meet a lot of consultants every year, and now and then I have to ask them what they don't do. The word covers a global strategy firm advising a boardroom, a solo IT or HR specialist, a tax or SEO consultant who handles one narrow function, a contractor who is a pair of hands for hire under a grander name, a salesperson whose "consultation" ends in a quote for their own product, a services firm selling staff augmentation, a coach, an advisor, and the between-roles executive who prints the title on a card while they look for the next job. The label alone tells you almost nothing. What tells you something is what the person does, and whether they have done it before. Now and then I hear an owner sum a consultant up as "engage me, I can do that."
In my definition, a business growth consultant works on the whole business to help it grow and become more commercially sustainable, and more valuable, with less of it depending on you. The work spans strategy, value, revenue, the leadership team, the systems, and getting the business ready to scale, to sell, or to transition. A good one is not a pair of hands you hire to run a project; there are specialists for that. They are an outside set of eyes, a sounding board who has seen the problem before, and the person who holds you to the plan once the meeting ends.
The difference from a specialist is breadth. A fractional CFO goes deep on the finances, a marketing agency goes deep on demand. A growth consultant works across the whole business and on you as the owner, which is where the biggest constraints sit, and they work back from where you want to be. My guide on the difference between a growth consultant and a fractional CFO goes into that comparison.
Is hiring a business growth consultant worth the investment?
The fee is visible and certain. The return is genuine but harder to see in advance, and that sense of risk, which they cannot easily control, is what makes owners hesitate. The plain way to weigh it: a growth consultant is worth the investment when the gap between where your business is and where you want it to be, within a timescale you care about, is bigger than you can close on your own, and when one better decision would pay for the engagement several times over.
For a middle-market business, the decisions a consultant helps you get right, where to focus, what to stop, how to price, who to promote, when to step back, how to prepare for an exit, are worth far more than the fee. The cost of trial and error on any of those dwarfs what an advisor charges. That is the case for it. The case against is just as important, so let me give you that too.
When a growth consultant is not worth it
I would sooner you not hire me than hire me and waste the money, time, and energy. A growth consultant is not worth it when:
- You will not act on the advice. If you want validation, not change, save your money. The value is in doing, and a consultant cannot want it more than you do.
- Your problem is purely a single function, most commonly finance. If you cannot see your numbers or cash is the issue, you need a fractional CFO, not a growth consultant.
- You want someone to do the work, not advise on it. If you need hands to run campaigns or build systems, hire a specialist or a contractor.
- You are too early. A pre-revenue startup needs customers and product, not a growth advisor.
- You already have the clarity and just need to execute. If the plan is sound and the team is capable, spend the money on execution.
- You have left it too late, with the business in decline for years and the bankruptcy buzzards circling. That is turnaround territory, not growth.
- You need to control everything. If you want to keep running a fiefdom, do not fool yourself. Save your time, money, and energy.
If any of those describe you, an experienced consultant will tell you so. The ones who say yes to everyone are the ones to avoid.
When a growth consultant is worth it
A growth consultant earns their fee when:
- Growth has stalled and you cannot see why, or you can see why but not how to fix it.
- The business depends on you, and you want it to run without you.
- You are scaling and the model, the team, or the systems will not stretch to match.
- You are preparing for an exit and want to lift the value and reduce the risk a buyer sees.
- You have no one who will tell you the hard truths. Every owner has blind spots, and the higher you climb, the fewer people challenge you.
- You are facing a transition, a new market, a big hire, a buyout, and you want a guide who has done it before.
- You are stressed and disillusioned, and the ways you have tried to fix it have not worked.
- The business now runs you, and you want to win back your time and lower your stress.
In each of these, the constraint is strategy, structure, people, skills, you, or some combination of them, and that is exactly what a growth consultant is for.
What return should you expect?
Be wary of anyone who promises a number. Growth is never guaranteed. It is a joint effort, and a consultant who pretends otherwise is only hoping. What you should expect is clearer decisions, sharper focus, expensive mistakes avoided, a stronger leadership team, faster profitable growth, and a business that is worth more and leans on you less. And there is experience to draw on, of what has worked for other owners in your position.
One example. I worked with the founder of an accounting managed-services business whose culture had turned toxic after a failed M&A deal. Rapid growth had put strains on the team that some people did not like, and others simply did not want to be in a business that size. When I advised them to focus on a culture strategy suited to their stage of growth, I told them that similar clients had seen around 25% of their headcount turn over. I remember the look they gave me, and the question, is that all? They went ahead. The churn tied directly to the work came in at 31%, and the ride was bumpy for the eighteen months it took to design, communicate, and embed what the culture stood for, how each value was defined, and how it would be managed. The year after, they won a Great Place to Work award, and kept winning it until the business sold. I provided the map. The owner and their team did the work to make the transformation they wanted.
Think of the return over twelve to twenty-four months, not twelve weeks. The compounding kind of value, owner-independence, a durable position, a capable team, takes time to build and then keeps paying back long after the engagement ends.
How to choose a business growth consultant
This is where a "business growth consultant review" should start, with the consultant, not the brochure. Look for:
- Have they run, and ideally sold, their own businesses? Advice from someone who has only ever advised is theory. You want someone who has carried the risk.
- A track record and references you can check. Ask to speak to owners they have worked with.
- The willingness to tell you hard truths. The best advisors disagree with you when you are wrong, early, before it costs you.
- Fit and chemistry. You will let this person deep inside your business. Trust and candor count for more than a slick deck.
- A clear scope and way of working. You should know what you are buying, the journey you are going on, how progress is measured, and how you part ways if it is not working.
- They can show how buyers assess a business, and whether, in a buyer's eyes, yours is commercially sustainable after a sale.
Be cautious of generic playbooks, rigid or fixed-length programs, pitches that promise the world, and anyone who has the same answer for every business before they have understood yours.
Questions to ask before you hire one
Ask any consultant you are considering: What businesses have you built or sold yourself? Where would you tell me not to spend my money? How will we measure whether this is working? Can I speak to business owners you have worked with? And, frankly, is my business one you can help right now, or not. The answers, and how directly they give them, tell you most of what you need to know.
Where I fit
For the brand-name searchers: I am Adrian Bray. I run Stellar Business Consulting in the US, and I am a business growth consultant and certified exit planner. I am also a chartered management accountant, a certified director, and a former international M&A advisor and consultant, and I have built and sold my own businesses across more than thirty years. I work with established middle-market owners, the ones with a sizeable team and genuine complexity, who are years from a sale or unsure they will sell at all, and who want a business worth more and less dependent on them. Part consultant, part peer who has sat in your chair. If that is the help you are weighing, the next step is a conversation about whether I am the right fit, and I will tell you if I am not.
FAQ
Is hiring a business growth consultant worth it?
It is worth it when the constraint on your business is strategy, focus, or your own dependence on it, and when one better decision would pay for the engagement many times over. It is not worth it if you will not act on the advice, if your problem is purely financial, or if you simply need hands to execute a plan you already have.
What does a business growth consultant do for your company?
They work across the whole business to help it grow and become more valuable, and to reduce how much it depends on you. That spans strategy, revenue, leadership, systems, and exit readiness. A good one is an outside set of eyes and an accountability partner, not a contractor you hire to run a project.
How much does a business growth consultant cost?
It varies widely by scope and seniority, from project fees to ongoing retainers. The more useful question is value, not price: a consultant is worth hiring when the decisions they help you get right are worth far more than the fee, which for a middle-market business they tend to be.
When should I hire a business growth consultant?
When growth has stalled, when the business depends too heavily on you, when you are scaling and the model will not stretch, when you are preparing for an exit, or when you have no one who will challenge your thinking. Each of these is a strategy or structure problem, which is what a growth consultant is for.
How do I choose a good business growth consultant?
Pick one who has run and ideally sold their own businesses, who will give you references, who tells you hard truths early, who fits how you work, and who is clear about scope and how success is measured. Avoid generic playbooks and anyone who says yes to every business before understanding yours.
Adrian Bray is a business growth consultant, certified exit planner, chartered management accountant, and former international M&A advisor who has built and sold his own businesses. He helps middle-market owners grow, build a business that runs without them, and prepare for an exit on their own terms. Part consultant, part peer who has been in your shoes. To talk through whether a growth consultant is the right move for you, get in touch.
Life After Selling Your Business: How to Plan a Next Chapter You Won't Regret
Key takeaways
- Most owners prepare the business and the deal, and leave the life after the sale to chance.
- The hard part rarely hits at closing. It arrives twelve to eighteen months later, once the holiday wears off.
- The money does not fill the gap left by identity, purpose, and structure.
- The owners who exit happily plan their next chapter with the same care they gave the deal, and start years early.
- This is the companion to the reasons owners regret selling. That piece explains the why. This one is the what next.
If you want to know why so many owners regret selling, I have written about that separately, around 75% profoundly regret it within a year, for a short list of reasons that are mostly about the person, not the price. This piece is about the other side of that problem: how to plan the life after the sale so you land in the 25% who step into something better, not the 75% who wish they had never signed.
I am a business growth consultant and a certified exit planner, and I spent years running an international M&A advisory firm, alongside building and selling my own businesses. I have watched owners close on life-changing numbers and then drift, because every hour of preparation went into the company and the deal, and none went into the life waiting on the other side. So this is the plan for the person, not the paperwork.
The honeymoon, then the void
The regret rarely shows up at the closing table. The first twelve to eighteen months feel good: the pressure lifts, you catch up with family, you travel, you play the golf you never had time for. It is the decompression you earned.
Then the quiet sets in. The calendar that was always full is empty. The problems that were always yours to solve belong to someone else. The phone that never stopped is silent. Around the eighteen-month mark, for many owners, the voice of regret starts to be heard, not because the deal was bad, but because nothing was built to step into. The holiday was the plan, and the holiday ran out.
Why the money does not fill the gap
Owners assume the proceeds will settle everything. They rarely do. Only a small share of owners report being happy with their net proceeds once tax, fees, and the loss of a tax-efficient income stream are accounted for, and for most owners the great majority of their net worth was tied up in the business, so the sale swaps a wealth-generating engine for a pile of capital that now has to be managed.
Money helps. It does not replace identity, purpose, daily structure, or the community a business gave you. A well-paid exit can still feel hollow, which is why the work that follows is about the life, not the bank balance.
The four questions to answer before you sign
Personal readiness comes down to four straight answers. Most owners cannot give them, and that is the warning sign.
Who am I without the business? For years the answer to "what do you do" has been the company. When it is gone, many owners feel a genuine void. Knowing who you are beyond the founder, before you sell, is what keeps the void from opening. I know I choked the first time someone asked, with nothing to offer but what I used to be, once the novelty of racing cars and digging divots on the golf course had worn off.
What will I do on the Monday after? Not the first month of travel, the ordinary Monday six months later. If you cannot picture how you fill a normal week with something that gives you purpose, that is the work to start now.
Who is it for, and what happens to it? Legacy, your team, and how the business carries on under a new owner mean a great deal to many founders. Getting clear on what you want to protect helps you choose the right buyer and the right terms, and softens the regret of watching someone else run what you built.
What part of me did the business satisfy? Most businesses start as a way to earn money and gain control, but they also carry some part of the owner's purpose. Understanding which part lets you meet that need in another form. When I realized that the cars and the golf did not satisfy my deeper purpose, bridging the divide to better futures for people who work hard, I started the chapter I am in now, doing what I do.
Plan the next chapter, not just the exit
The owners who exit well treat the sale as a doorway, not a destination. They decide what they are walking toward before they walk through it.
Give yourself something that excites you, uses what you are good at, and feeds that sense of purpose. For many former owners that is mentoring younger entrepreneurs, investing in or advising other businesses, taking board seats, philanthropy, or building something new on a smaller, lower-stakes scale. The point is a next chapter with purpose and a scoreboard, not an open-ended holiday.
Make it concrete. "I'll figure it out" is how owners end up adrift. A plan you can describe, with people in it, a rhythm to your week, and a reason to get up, is what carries you across the gap that swallows so many.
Build the identity bridge while you still own it
The best time to become someone other than the founder is while you are still the founder. Step back from the daily run of the business, hand genuine responsibility to your leadership team, and start building the parts of your life that are not the company, the interests, the relationships, the roles that will still be there after the sale.
This does two things at once. It makes the business less dependent on you, which raises its value and makes it more sellable, and it gives you an identity that survives the exit. My guides on building an owner-independent business and on building lasting value cover the business side of stepping back. The personal side runs in parallel: the more of your life exists outside the business before you sell, the softer the landing.
A personal-readiness timeline
Run your personal preparation alongside the business preparation, over three to five years, not in the final months.
Years out, start widening your life beyond the business and testing what a next chapter might be. Take on an interest, a board, a cause, and see what holds your attention. In the middle years, step back from the daily operation and let the leadership team carry more, so you experience a version of life with the business at arm's length. As the sale approaches, bring your family fully into the conversation, because the transition is theirs too, and lock down the picture of what comes next so the day after closing has a shape. Done this way, the sale is a step into a life you have already started living, not a leap into an empty one.
If you have already sold and feel the gap
If you are reading this on the other side, restless or flat despite a good deal, you are in good company, and it passes. The same steps work after the fact. Find the thing that gives you purpose, rebuild a structure to your weeks, and put decades of hard-won experience to use through mentoring, investing, advising, or building again. The owners who recover fastest are the ones who give themselves a new mountain to climb.
Where to start
Answer the Monday question plainly: if the business sold this quarter, what would you do with the Monday three months later, and the one after that. If you cannot answer, that is the most important work you can start now, long before any deal. Prepare the person, not just the business and the paperwork.
This is the part of an exit I care about most, drawing on years of taking owners to market and on selling my own: making sure the deal that looks good on paper becomes a life you are glad you stepped into. For the reasons owners come to regret selling, see my companion piece on exactly that. If you want help planning the life on the other side, that is what I do.
FAQ
What is life after selling a business like?
For most owners the first twelve to eighteen months feel like a well-earned break. After that, many feel the loss of identity, purpose, and structure the business gave them. The owners who enjoy life after the sale are the ones who planned a next chapter before they signed, instead of treating the deal as the finish line.
What should I do after selling my business?
Build a next chapter with purpose and structure: mentoring, investing, advising, board work, philanthropy, or building something new at a smaller scale. Give your week a rhythm and a reason to get up. The aim is a plan you can describe and feel excited about, not an open-ended holiday.
How do I prepare for life after selling my business?
Start years ahead and run it alongside preparing the business. Widen your life and identity beyond the company, step back so the leadership team carries the daily load, bring your family into the decision, and define what your next chapter looks like before you sell.
Will I regret selling my business?
Around 75% of owners do, within a year, and it is rarely about the price. The regret comes from losing identity and purpose with no plan for what is next. Preparing yourself, not just the business, is what puts you in the 25% who do not regret it. I cover the reasons in detail in a companion article.
How long does it take to adjust to life after selling?
It varies, but the difficult stretch tends to begin after the first year, once the decompression period ends. Owners who planned a purposeful next chapter in advance adjust far faster than those who left it to "I'll figure it out."
Adrian Bray is a business growth consultant, certified exit planner, chartered management accountant, and former international M&A advisor who has built and sold his own businesses. He helps middle-market owners grow, build a business that runs without them, and prepare for an exit on their own terms. Part consultant, part peer who has been in your shoes. To plan a next chapter you will not regret, get in touch.
Why Most Businesses Don't Sell (and How to Be the Exception)
Key takeaways
- Most businesses that go to market never sell, and the smaller the business, the lower the odds.
- The headline stats are estimates. The data on private deals, and on the ones that fall through, is patchy.
- Deals fail for a short list of reasons: a valuation gap, weak financials, a business that depends on its owner, and a seller who is not ready.
- Even most owners who do sell regret it within a year, because they prepared the deal but not themselves.
- All of this is avoidable with enough runway, which is the whole case for building value and getting ready early.
You did the hard part. You founded the business, beat the odds that sink most startups, and built something that means a great deal to you and supports other people. So the quiet fear that it might not sell when the time comes, that the work might not convert into the result you earned, is a genuine one. It deserves a straight answer.
I am a business growth consultant and a certified exit planner, and I spent years running an international M&A advisory firm, taking owners to market and pulling comparable deals from the industry databases myself. So I will give you the straight version of why most businesses do not sell, what the numbers say, and how to make sure yours is one of the ones that does.
What percentage of businesses sell?
You will see the line everywhere, on podcasts, on LinkedIn, in YouTube hooks: "80% of businesses fail to sell." It is partly true, and partly a headline.
It holds up best at the smaller end. For a business below about $5 million in revenue going to market, the odds of completing a sale are genuinely poor. As businesses get larger and are valued and assessed on a multiple of EBITDA, the story improves, but an exit is still never a done deal. Industry estimates from the IBBA and M&A Source Market Pulse surveys line up roughly like this:
| Business size (EBITDA) | Chance of not selling | Chance of selling | Typical time to sale |
| Under $500K | 85-90% | 10-15% | 12-18 months |
| $500K - $1M | 75-80% | 20-25% | 10-14 months |
| $1M - $3M | 70-75% | 25-30% | 9-12 months |
| $3M - $5M | 50-60% | 40-50% | 8-10 months |
| Over $5M | 30-40% | 60-70% | 6-9 months |
Source: estimates drawn from IBBA and M&A Source Market Pulse data.
Size affects this for a simple reason: it shapes who will buy. Private equity, say, wants at least $2 million in EBITDA, and ideally $3 million or more, before a business is interesting as a standalone or a platform. Below this you might be an eligible add-on, a consolidation play to help build a bigger business, but the deal terms will carry some bias toward that future payday, and more risk for you. Otherwise the buyer pool thins, and a thinner buyer pool means longer odds.
Why the numbers are softer than they look
Treat every one of these figures as an estimate, including mine. The databases the M&A industry relies on for privately held transactions are incomplete, and advisors vary in their willingness to feed the data machine. They capture a fraction of deals, they vary in quality, and, most important, they rarely record the deals that did not complete. A statistic built mostly from successful sales cannot tell you much about the failures.
I learned this firsthand searching those databases for comparables and trends when taking clients to market. The picture is always partial. So use the numbers to understand the shape of the problem, smaller businesses sell less readily, exits are never guaranteed, but do not treat any single percentage as gospel. The useful truth is directional, and it is sobering enough on its own.
Why most businesses don't sell
When a sale falls apart, it is rarely a mystery. A short list of causes does most of the damage, and every one of them is something you can fix with time.
The valuation expectation gap
The single biggest deal killer is the distance between what a seller wants and what a buyer will pay. Estimates put this behind somewhere from a third to well over half of failed sales, depending on industry and size. The cause is that the seller ignores, or never learns, the benchmark multiples for their business and builds their own number instead.
Call it the country club method: pricing the business on what you heard another owner got, or on what you feel you need to match or beat a peer. That number gets anchored by the family name, emotional attachment, the sacrifices you made, the hours you put in, and the potential you are sure is still ahead. None of those is what a buyer pays for. A buyer pays on how the business performs against the benchmark for its sector and size. When the seller's number and the market's number are too far apart, the deal never starts. My guide on increasing your business valuation covers how that benchmark works and how to move your business up it.
Weak financial records
Poor financials sink a large share of deals, by most estimates somewhere around a fifth to a quarter. The usual suspects: personal and business spending blended together, missing tax returns, management accounts that do not reconcile to those returns, undocumented cash moving in and out, accounting that changes from one year to the next, and unexplained jumps or dips in revenue and costs, especially in the last eighteen months, that look like they might be hiding something.
Buyers price uncertainty as risk, and risk as a discount or a walk. Surveys suggest more than three quarters of buyers will walk away when a seller cannot produce at least three years of clean, properly compiled accounts that map to their tax filings. My checklist on whether your business is ready to sell goes through exactly what a buyer needs to see.
The business depends on the owner
A business that cannot run without its founder is hard to sell at any price, because any buyer is acquiring a job, not an asset. The Exit Planning Institute puts owner or key-person dependence behind around 20% of failed deals. The warning signs are concrete:
- No capable management team beneath the owner.
- The owner, or one or two key people, personally performs the specialized technical or delivery work.
- No documented systems or procedures.
- The owner controls purchasing and the key supplier relationships.
- A handful of people hold more than 70% of the customer relationships, or relationships that drive more than 70% of revenue.
There is a sharper version of this risk when the key people are not the owner but a small group nearing retirement with no stake in the outcome. This single factor commonly sits underneath the others: it depresses the valuation and makes the seller hard to replace in the buyer's eyes. It is the most common reason a smaller professional-services firm is, in practice, unsellable, and bigger firms tend to hire the people as an acqui-hire, not a firm purchase. Building a business that runs without you is the surest way to fix it, and my guide on owner-independence is the deepest treatment of it in this series.
The seller is not ready
Some deals die not because of the business but because of the owner. This covers sellers who were never fully committed, owners whose circumstances change mid-process, and the ones who pull the deal at the last moment. Together with deals that collapse after the letter of intent, this accounts for a meaningful slice of failures.
I once had a seller pull out the night before signing. We had beaten his wildest expectations on both valuation and cash at close. The business was ready. He was not. He could not face telling his family the next day that it was done, and he would have to lay two of them off. We had prepared the deal and not the person. It is the reason I now look hard for the signs of personal readiness early in any engagement, long before a term sheet is on the table.
The pattern shows up in a handful of ways: a seller who wants to test their ego and the market with no genuine intent to follow through, an owner who realizes too late that their whole identity is the business, a spouse who was never truly part of the decision, or who does not want their partner at home all day upending the life they have built, a business put up for sale during its own slump or a soft market, or a change of heart when health improves, the business recovers, or family circumstances move. Buyers and advisors burn serious time and money on these in good faith, and the industry has a name for the seller who does it repeatedly: a well poisoner. Those sellers get known, and the better buyers learn to avoid them.
Deals that fall apart in due diligence
Even a signed letter of intent is not safety. You are at the altar, and the deal can still break up before the wedding. Axial's 2025 Dead Deal Report, which examined 75 broken deals in the lower middle market ($2.5 million to $250 million), found that most letters of intent now collapse in diligence, not over financing. The leading causes:
- Non-financial diligence findings, around 25%: legal or compliance risks, undisclosed customer concentration, or contracts that will not transfer.
- Quality-of-earnings gaps, around 21%: the true EBITDA does not match the story the seller told.
- No agreement on a repriced deal after diligence, around 15%.
- The seller walking away, around 13%.
- Buyer financing or appetite cooling once the facts are clear, around 11%, with performance dips during the process and other causes making up the rest.
The trend over recent years is toward diligence findings and earnings gaps, and away from financing. The lesson is the same: deals die when diligence surfaces something the early conversations glossed over. Preparation is what keeps a deal alive, because there are no surprises left to find. (Source: Axial 2025 Dead Deal Report.)
Deals also die over terms, not just price
Even when buyer and seller agree a headline number, the deal can fail over how that number is paid. Middle-market buyers will not pay full cash for a business that carries serious risk, so they structure the price to share it. The further down this list you go, the more risk sits with you:
- Cash at closing: no risk once the money transfers.
- Working capital adjustments: a little risk.
- Revenue earnouts: some risk, plus the distraction of hitting targets while the business absorbs the sale.
- Profit-based earnouts: more risk, especially if new costs land on the P&L after completion.
- Growth-based earnouts and rolled-over equity: the most risk, and in the case of equity, a second outcome that depends entirely on what the new owner does next.
Sellers who have not thought about structure fixate on the headline and are blindsided by the terms. According to IBBA and Axial research, the mix of cash and earnout, working capital adjustments, non-compete scope and duration, and the financing behind the deal are all common points where an agreed price still falls apart.
The hidden cost: even sellers regret it
Selling is not the finish line you think it is. The Exit Planning Institute's research finds that around 75% of owners profoundly regret selling within a year of the deal. The reason is rarely the price. It is that they planned the transaction and not the life after it, walking away from the identity, the purpose, and the structure the business gave them with no plan for what comes next.
This is the same lesson as the seller who pulled out the night before, seen from the other side. A good exit is more than a clean financial deal. It is one you are personally ready for. Building value gets you the offer. Getting yourself ready is what lets you accept it and not regret it.
How to be the exception
Every reason on that list has the same antidote: start early, and prepare both the business and yourself.
Know your benchmark, not your country-club number, so your expectations and the market's are in the same place. Clean your financials years ahead, so a buyer trusts them on sight. Reduce the business's dependence on you, so a buyer is acquiring an asset and not your calendar. And prepare yourself, your plan, your purpose, and your answer to "what next," so you do not freeze at the table or regret it afterward.
That is the whole case for treating value and readiness as a multi-year project, not a last-minute scramble. My guides on building lasting value, exit planning, and whether your business is ready to sell each take one piece of it in depth. The owners who sell well, and stay glad they did, are almost always the ones who started this work long before they needed to.
Where to start
Get a clear-eyed, benchmark-based read on two things: what your business is worth today, and how ready it, and you, would be if a buyer appeared next quarter. The gaps you find are your plan. Most of them take years to close, which is exactly why the time to start is now, well before you intend to go anywhere.
This is the work I do with owners, drawing on years of taking businesses to market and on building and selling my own: close the gaps that cause deals to fail, build the value that earns a strong offer, and get you ready for the life on the other side. If you want to make sure your business is one of the ones that sells, and sells well, that is what I help with.
FAQ
What percentage of businesses sell when they go to market?
Most do not, and the odds track size. For businesses under about $5 million in revenue, the majority that list never complete a sale. Larger lower-middle-market businesses, valued on EBITDA, sell more readily but still face genuine failure rates. Treat the headline numbers as directional estimates, because data on private and failed deals is incomplete.
Why do business sales fail?
The main causes are a gap between the seller's price and the market's, weak or unverifiable financials, a business that depends too heavily on its owner, and a seller who is not personally ready. A further share of agreed deals collapse in due diligence when something surfaces that earlier talks glossed over.
Why won't my business sell?
It comes down to one of four reasons: your asking price sits above the benchmark for your size and sector, your financials are not clean enough for a buyer to trust, the business leans too much on you, or the offer arrived before you or the business were ready. Each one is fixable with enough lead time.
Is it true that 80% of businesses don't sell?
It is roughly true at the smaller end of the market and softens as businesses get larger. It is also an estimate built on incomplete data, since failed and private deals are poorly recorded. The plain takeaway is that selling is far from guaranteed, especially for smaller businesses, so preparation counts.
Do most owners who sell regret it?
Research from the Exit Planning Institute finds around 75% of owners profoundly regret the sale within a year, because they prepared the deal but not their own next chapter. Building value gets the offer, personal readiness is what makes the exit one you are glad you took.
Adrian Bray is a business growth consultant, certified exit planner, chartered management accountant, and former international M&A advisor who has built and sold his own businesses. He helps middle-market owners grow, build a business that runs without them, and prepare for an exit on their own terms. Part consultant, part peer who has been in your shoes. To find out where your business and your exit stand, get in touch.
How to Increase Your Business Valuation Before You Sell
Key takeaways
- Your business value is not fixed. Most of it is built in the two to three years before you sell.
- Valuation for most buyers is earnings times a multiple, and the multiple is set by how risky and how scalable a buyer thinks the business is.
- The biggest risk levers are reducing dependence on you, predictable revenue, customer spread, clean financials, and a credible growth story.
- The biggest scale levers are transferable skills and capabilities, culture, channels, systems, positioning, brand, and a scalable product or service model.
- The highest price can come from a prepared business taken to several buyers who want the scale levers at once, not a single unplanned offer accepted in a hurry.
Most owners discover what their business is truly worth at the worst possible moment: when a buyer puts a number in front of them. By then the value is set, and it is lower than they hoped. The owners who sell well find out years earlier, see the gap between today's value and the price they want, and spend the time before a sale closing it.
I am a business growth consultant and a certified exit planner, and I have built and sold my own businesses. I have watched two companies with the same profit sell for very different sums, because one had done the work to look low-risk and the other had not. So this is the work I help owners with, and it is work I have done on my own businesses. Value is something you build, not something you wait to be told.
This guide covers how a business is valued, the factors that move that figure most, the levers that increase it, and how to turn a higher value into a higher price when you sell.
How is a business valued?
For most middle-market businesses, value comes down to a simple shape: earnings times a multiple. Earnings is your sustainable profit, adjusted for one-off costs and owner perks, commonly expressed as EBITDA or, for smaller firms, seller's discretionary earnings (SDE). The multiple is the number a buyer applies to those earnings, and it reflects how much risk and how much growth they see.
Two businesses can make the same profit and sell for very different prices, because one commands a higher multiple. A business that depends on its owner, leans on a few customers, and grows slowly carries a low multiple. A business that runs without its founder, has predictable revenue, and shows a clear path to growth commands a high one. Increasing your valuation means lifting one or ideally both numbers: growing sustainable earnings, and raising the multiple by lowering risk and making the business more scalable.
Revenue and EBITDA sit at the center of the equation, and they do different jobs. Revenue shows the current momentum of the business, how large it is and how fast and how reliably it is growing. EBITDA, your earnings before interest, tax, depreciation, and amortization, shows how much of that revenue turns into genuine profit, and then into cash. A buyer reads them together. Strong revenue growth and a healthy EBITDA margin earn a higher multiple than either one alone, while a business growing fast but barely profitable, or profitable but flat, leaves value on the table. Most middle-market businesses are valued on a multiple of EBITDA, though fast-growing or recurring-revenue models can be priced on a multiple of revenue instead, depending on the buyer's objectives.
The multiple benchmark, and the two forces that move you off it
Every industry has a benchmark multiple, also called the industry average. It rises and falls with the sector and the stage of the economic cycle, and you cannot change the average. What you can change is whether your business is priced above or below it. Many business owners don't realize this, and much small and middle-market valuation advice focuses only on operations, or the auction sale process, which is only part of the story.
Two forces decide whether you are priced above, at, or below the benchmark. Risk levers pull you below it, because they make a buyer nervous about what they are taking on. Scale levers push you above it, because they show how much bigger the business could become, but only once the risk levers are well managed. A buyer rarely pays for growth potential in a business they do not trust to run without its owner. Manage the risk first, then the scale levers do their work.
How do you compare to your peers?
A multiple is not set in a vacuum. Buyers and valuers benchmark your business against comparable companies, recent deals, and the industry average in your sector, the risks inside those businesses and the scale levers they carry. They look at how your revenue growth, EBITDA margin, and other measures stack up against the typical performer in your space, and they factor that into their read on your risk and scale levers.
This cuts both ways. A business with a higher EBITDA margin or faster growth than its peers earns a premium when it is outperforming its market, and that outperformance can be linked to the scale levers and to confidence that the risk levers are well managed. One that lags the peer median on margin or growth gets marked down, because the buyer reads the gap as weakness and poor risk management in how the business is run.
The practical value of benchmarking is that it turns "increase the value" into specific targets. If your margin sits below the peer median, closing that gap lifts both your EBITDA and the multiple applied to it, a double gain. If your growth lags against your sector and size of business, that is the number to work on. Get the margin toward the top quartile for your sector and lift growth to match the leaders, and the valuation follows.
What pulls your multiple down: the risk levers
Risk levers are the things that make a buyer nervous, and each one drags your multiple below the industry benchmark. Every one of them is fixable, and fixing it is the fastest route to a higher multiple. One challenge for founders is that they are comfortable with these risks. After all, it took the confidence to back themselves to build the business in the first place. But buyers almost always have a lower risk tolerance than founders, so what feels normal to you can read as danger to them.
Owner dependence. A business that cannot run without you is the single biggest discount most owners carry and can easily halve the industry multiple benchmark. If you are the main salesperson, decision-maker, and problem-solver, a buyer sees the risk that performance leaves when you do. Close it by building a leadership team that decides without you, documenting the processes that make the money, and moving customer relationships to the company. My guide on building an owner-independent business walks through how.
Unpredictable revenue. One-off sales are worth less than predictable income a buyer can count on, because every month or quarter starts from zero. Convert work into contracts, retainers, or subscriptions where you can. Even shifting part of your revenue from one-off to recurring lifts the multiple.
Customer concentration. If one customer is a large share of revenue, losing them could sink the business, and a buyer prices that danger in. Win a wider spread of customers so no single account can take you down, and the risk a buyer sees falls with it.
Weak financials. Messy or unprovable numbers invite discounts, because a buyer assumes the worst about anything they cannot verify. Separate personal and business spending, document your add-backs, and produce three years of clean accounts, ideally five, that map cleanly to your tax returns. Owners who do this a few years ahead sell for more, because the buyer and their team stop hunting for hidden problems.
Thin margins and flat growth. Both point to a business that is stalling, with rising costs, or simply hard to run. Tighten pricing and manage cost to lift the margin, and build an evidenced plan that shows where the next phase of growth comes from. Get your margin and growth to the benchmark for your sector and the discount disappears.
What pushes your multiple up: the scale levers
Once the risk levers are managed, scale levers lift you above the benchmark. They tell a buyer the business can be bigger under their ownership, and the potential transfers with the company instead of walking out with you.
Market position. A defensible position, a brand and reputation a buyer can build on, tells them the business stands for something durable, and you don't have to be a household name for it to count. Sharpen what you are known for and who you are known to, so your position is clear, aligns with the other growth levers, and is hard to copy.
Repeatable channels. Sales and marketing engines aligned with your position that bring in customers without you driving each deal are worth a premium, because a buyer can scale them up. Build channels that produce pre-sold customers predictably, and document how they work.
Transferable capability and culture. Operational and strategic know-how that lives in your team, not your head, and a culture that performs and renews itself as it grows, both turn the business into an asset that keeps producing after you leave. Develop your people and write down what makes the work excellent, the skills, the processes, the tools, and the unique combination that creates your edge.
Systems that scale. Documented systems, processes and workflows are the difference between a business that grows smoothly and one that strains under its own weight. Build and record them as you go, so a buyer can grow the business without it breaking.
A scalable model. Where it fits, shape a product or service model that grows revenue without growing cost at the same pace. Do you know your current capacity? That headroom earns the highest multiples, because the buyer is acquiring a platform, not just a profit stream.
A de-risked business sells. A de-risked, scalable business commands the top of the range. My checklist on whether your business is ready to sell scores where you stand on each of these levers.
How to maximize your sale price when you sell
A higher valuation sets the ceiling. Maximizing the price is about reaching it. Four things decide whether you do.
Manage your levers. A well-run business manages down the risk levers to a level well below the buyer's risk tolerance. It also creates transferable business assets that the buyer can scale when they apply their additional resources.
Create competition. A single buyer with no rival sets the price. Several interested buyers let you set it. Taking the business to market in a way that brings more than one credible buyer to the table is the surest way to lift the final number.
Time it well. Buyers move in cycles, by sector and by their own appetite. A prepared business taken to market when buyers are active sells for more than the same business offered when they are not. Being ready means you can move when the window opens.
Get the structure right. How the deal is structured, and how your affairs are arranged ahead of it, can change what you keep by a large margin. This is specialist work that needs time, which is one more reason to prepare early. My guide to exit planning covers the full process.
Quick wins versus long-term value building
Some moves lift value within months: cleaning up the books, documenting your top processes, and tightening obvious pricing or cost gaps. These are mostly risk fixes, and they pay back fast as they start to make you more buyable. Others take years and move the value most: building a leadership team, shifting revenue to recurring, and building the scale levers. Do both. Start the quick risk fixes now for momentum, and begin the long scale builds early because they need the time.
Common mistakes
Waiting until a buyer appears to think about value, when the gap can no longer be closed. Allowing your ego to confuse what you want the business to be worth with what it is worth today. Leaving the business dependent on you, which caps the multiple. Carrying messy financials a buyer cannot verify. And accepting the first offer without creating competition, which leaves money on the table.
Where to start
Get an independent valuation, an assessment of the health of your risk and scale levers, and a clear-eyed read on where you sit against your industry benchmark. The gap between today's value and the price you want is your plan, and most of it initially comes down to risk levers you can remove and scale levers you can build. Start with the financials and your dependence on the business, because they move the multiple more than anything else.
This is the work I do with owners as a business growth consultant and certified exit planner: find what is holding your value down, rank the fixes by how much they move the price, and close the gap in the years before you sell. I have built businesses, sold them, and helped other owners lift their value before going to market. If you want a clear read on what your business is worth and how to raise it, that is what I do.
FAQ
How can I increase the value of my business before selling it?
Lift sustainable earnings and move your multiple above your industry benchmark. Manage the risk levers that pull you below it, owner dependence, unpredictable revenue, customer concentration, weak financials, and thin margins, then build the scale levers that push you above it, market position, repeatable channels, transferable capability, systems, and a scalable model. Most of this takes two to three years to do well.
What factors most affect business valuation when selling?
Two sets of factors move your multiple off the industry benchmark. Risk levers pull it down: dependence on the owner, unpredictable revenue, customer concentration, weak financials, and thin margins or flat growth. Scale levers push it up: market position, repeatable channels, transferable capability and culture, documented systems, and a scalable model. Manage the risks and build the scale, and the multiple rises.
How do I maximize my business sale price?
Build the value first, then create competition among buyers so more than one is bidding, time the sale to when buyers in your sector are active, and get the deal structure and tax planning right. A prepared business sold into a competitive process reaches a far higher price than one sold to a single buyer in a hurry.
How is business value measured before a sale?
For most middle-market businesses, value is sustainable earnings (EBITDA in most cases) times a multiple. The multiple reflects how risky and how scalable a buyer thinks the business is, so two businesses with the same profit can sell for very different sums.
How long does it take to increase a business's valuation?
The quick wins, like cleaning financials and documenting processes, take months. The biggest levers, like building a leadership team and shifting revenue to recurring, take two to three years. Starting early is what lets the value build before you sell.
Adrian Bray is a business growth consultant, certified exit planner, chartered management accountant, and former international M&A advisor who has built and sold his own businesses. He helps middle-market owners grow, build a business that runs without them, and prepare for an exit on their own terms. Part consultant, part peer who has been in your shoes. To find what is holding your value down and close the gap, get in touch.
How to Build an Owner-Independent Business in 2026
Key takeaways
- An owner-independent business keeps running, selling, and serving customers when you are not there.
- Five systems make it possible: a leadership layer and system that decides without you, documented operational processes, company-owned customer relationships, numbers you can read at a glance, and a culture that outlasts you.
- The fastest test is the ninety-day question: if you vanished for three months, what would break.
- Start by writing down the decisions only you make, then hand them over one at a time.
A business that depends on you is a job you cannot quit. It pays you, and in return it owns you, your calendar, your holidays, and your phone at the dinner table. An owner-independent business does the opposite. It runs, sells, and serves customers whether you are in the building or on a beach. I've seen $100M businesses be more owner dependent than some $6M ones. I've also watched owners revel in the dependence and their role as chief whack-a-mole officer and wonder why the business is unattractive to buyers or investors.
At your size the dependence rarely looks like doing all the work yourself. The team runs the day-to-day. The catch is that strategy, the biggest client relationships, the hiring calls, new service lines or products, and every decision that carries weight still route back to you. The business has a team, but it does not yet have an owner who can leave.
I learned this the hard way. My first businesses ran through me. Every quote, every hire, every unhappy customer found its way to my desk, and I called that being indispensable. At first it felt important. It was the opposite. I had built something fragile that could not grow past my own hours and was effectively unbuyable. I had built it in my father's image, the owner at the heart of every decision, because that was one of only two models I had ever seen up close. The other was the global corporate I came from, all process and little soul, and just as wrong for what I wanted. Neither showed me the business I needed: one that could run without its owner and still feel like mine. That gap is who I work with now. Most advice is built for the corporate boardroom or the smaller main-street business. The established middle-market business, with a sizeable team and genuine complexity but no corporate machine behind it, gets left to translate advice that was never written for it. So I write this as the consultant who now helps owners fix it, and as the owner who once lived inside the problem.
This guide covers what owner-independence means, why it sets the value of your business, and the systems that get you there.
What is an owner-independent business?
An owner-independent business is one that keeps performing without the founder or owner making the daily decisions. The leadership runs operations, the processes are written down, customers belong to the company and not to you personally, and the numbers tell everyone whether things are on track.
Owner-independence is a spectrum, not a switch. Most founders sit further toward the dependent end than they think. For many they started the business as a way to earn an income and have control, yet as it grew the business gained control over them. The goal is steady movement toward the other end, where the business could carry on for months without you and a buyer would pay a premium for that stability.
Why owner-independence sets your value
Two businesses with identical profit can sell for very different sums. The one that needs its founder in the room every day carries a discount, because the buyer is acquiring a risk: the day you leave, the performance might leave with you. The one that runs on its own commands a higher multiple, because the buyer is acquiring a machine that keeps producing.
The same quality that raises the sale price also improves your life today. A business that does not need you is easier to grow, simpler to delegate, and far less likely to collapse under a single point of failure, which is you.
Part of the problem I have found is that of identity and the owner's relationship with the business. It gets hard to let go when the business is who you are, carries your name, or is how you express your purpose in life.
Here is the test that cuts through it. If you disappeared for ninety days with no phone, no wifi, and no laptop, what would break. Write the list. Each item is a piece of owner-dependence, and each one is a task on the plan below.
The five systems that make it run without you
1. A leadership layer that decides without you
If every decision above a small size waits for your approval, you are the ceiling, the choke point. Strengthen and empower the leadership layer you have, the managers who own outcomes, not just tasks, and give them the authority to match. If you do not yet have that layer, building it is your first piece of work. Either way the aim is the same: agreed decision rights, responsibilities, budget, clear targets, and the freedom for your leaders to get things wrong and learn how to fix them without you stepping in to rescue them.
Start by listing the decisions only you make and the meetings that you must attend. Sort them into three groups: hand over now, hand over after some coaching, and keep for now. The first group is bigger than you expect.
Handing decisions over is not abdicating them. You still need to know things are on track, and so do your leaders. That is what the numbers in system four are for: a clear line of sight that lets you let go without flying blind. Delegation without visibility is a gamble. Delegation with a feedback loop is how you step back and keep control of the outcome.
2. Documented processes for the work that earns money
Knowledge living only in your head is a liability a buyer pays less for, and a bottleneck that slows your team every day. Write down how the money is made: how you win customers, deliver the work, invoice, and handle the problems that recur. I once held a specialism only six people in the world had, and thousands of corporations needed it. Some clients wanted to hoard that knowledge. It made me the bottleneck, on a plane to a different city every week, and it severely limited our growth. That is exactly the kind of knowledge that has to come out of your head and into the business.
You do not need a heavy manual. Short, usable checklists and simple recorded walkthroughs beat a polished binder nobody opens.
Begin with the processes that break most when you are away, then work through the rest. How could you use AI or a digital-first approach to carry more of it?
A simple way in: the next time you do one of these tasks, record your screen or talk through it as you go. Hand that recording to the person who will own the process and ask them to turn it into a short checklist, then run it while you watch once. They will catch the steps you forgot you knew. Each process you capture this way is one more thing the business no longer needs you for.
3. Customer relationships the company owns
If your biggest customers buy because of their personal bond with you, the business cannot be handed over or sold cleanly. Move those relationships to the company. Introduce account owners from your team, put agreements in writing, and make sure the value customers receive comes from the business and its people, and not from you alone.
Understand what their fears could be by losing the connection with you and demonstrate how your replacement is a far better choice to support their needs and connection with your business.
Move the relationships on purpose, not all at once. Pick one important account and introduce the team member who will own it alongside you. Reassure the customer they keep a direct line to you. Bring the new owner into the meetings, hand them the day-to-day contact, and let the customer see the team solving problems while you are still in the room. Step back in stages until the account runs through your colleague and barely notices you are no longer in the room. Then do the same with the next one.
4. Numbers you can read at a glance
A self-running business needs a simple set of numbers that tell everyone whether things are healthy and predictable: revenue, pipeline, cash, margin, and a few measures specific to how you deliver. When the team can see the score without asking you, they can steer without you. A one-page dashboard, reviewed on a fixed rhythm, replaces the constant questions that otherwise land on your desk.
This is also what makes delegation safe. When the right numbers are visible on a regular rhythm, you can hand over decisions and still see at a glance that they are working out, and your leaders can act knowing the same. The dashboard gives them the confidence to decide and gives you the confidence to stay out of it. Set the cadence, a weekly or monthly review, and let the numbers raise their hand when something needs you, instead of you checking on instinct.
5. A culture that outlasts you
In professional services the business is its people. The work walks out of the door every evening and decides whether to come back. If the culture runs on your energy, your standards, and your presence in the room, it leaves when you do, and the talent that culture keeps leaves with it.
As my businesses grew, this is the system that changed the most. When we were a small team we ran on informality. Most of the managing happened over a monthly pint down at the pub, and at that size it worked. By the time we were fifty, then seventy-five, it did not. We needed structure and conscious management of the culture: deliberate choices about the values we hired for, how we developed people, and how we kept the way we worked intact as faces arrived who had never known the business when it was small. What once spread by osmosis now had to be built on purpose.
Build a culture that does not need you in three ways. Make your values and standards explicit, so they guide decisions when you are not in the room. Build hiring, onboarding, and development that reliably produce the kind of people the business runs on. Grow leaders who carry the culture, so it spreads through them instead of radiating from you.
A buyer reads this closely. High staff turnover, key people who might leave with you, or a culture that is only your personality all register as risk. A team that stays, performs, and renews itself without the founder is one of the clearest signs the business can outlast your exit.
What systems do I need to make my business sellable?
A buyer is checking whether the business survives your exit. The five systems above answer that directly: leadership that runs operations, documented processes a new owner can follow, customer relationships that transfer, clear numbers that prove the business is steady, and a culture and team that stay after you go. Add clean financials and tidy legal ground on top, and you have a company that reads as low-risk and sells for more. The work that makes a business sellable is the same work that makes it run without you.
A 90-day path to step back
You do not rebuild everything at once. Take it in quarters.
In the first thirty days, write the ninety-day list of what would break without you, and pick the three pieces of owner-dependence that scare you most. In the next thirty, hand over the first set of decisions to your leadership layer and document the two or three processes that fail most when you are away. In the final thirty, take a deliberate week out of the daily run, watch what breaks, and fix those gaps. Then repeat the cycle with the next three items.
Owner-independence is built one handover at a time. Each one buys back a little of your week and adds a little to the value of the business.
Where to start
Run the ninety-day test this week and write the list. It shows you, in your own words, exactly where the business leans on you. Consider color coding them, are they related to strategy, culture, revenue, or infrastructure?
Then look at your calendar, not just the tasks you do. Go through a typical month and mark every meeting you sit in. For each one, ask why you are there and what would happen if you were not. The meetings where the straight answer is "it would be fine" are the first ones to hand over. The meetings where the answer is "it would fall apart" show you exactly where the business still runs through you, and what to build next.
Decisions and documented processes free up the most time fastest, so start there.
This is the work I do with owners as a business growth and exit readiness consultant: find the functions that depend on you, build the leadership and systems to replace that dependence, and give you a business you could step away from or sell on your terms. I have stood where you are standing, running a business that could not run without me, and climbed out of it. If you want help building the same independence into yours, that is what I do.
FAQ
How do I build a business that doesn't depend on me to run it?
Build five systems: a leadership team with the authority to decide, written processes for how the money is made, customer relationships owned by the company, a simple set of numbers everyone can read, and a culture that keeps its standards without you. Hand over the decisions only you make, one at a time, and document the work as you go.
How do I build a self-running business?
Use the ninety-day test to find every point that depends on you, then replace each one with a person, a process, or a number. Work in quarterly cycles: hand over decisions, document the work, take time out to see what breaks, and fix the gaps.
What systems do I need to make my business sellable?
Leadership that runs operations without you, documented revenue processes a new owner can follow, customer relationships that belong to the company, clear numbers that show the business is steady and growing, a culture and team that stay after you exit, plus clean financials and tidy legal ground. Together they tell a buyer the business survives your exit.
How long does it take to build an owner-independent business?
Most owners see meaningful change within a year of focused work, with the first handovers freeing up time inside the first quarter. The deeper the current dependence on you, the longer the climb, but every cycle moves you forward.
Where do I start if everything runs through me?
Write the list of what would break if you vanished for ninety days. Pick the three items that worry you most and hand over or document those first. Momentum comes from finishing the first three, then choosing the next three.
Adrian Bray is a business growth consultant, certified exit planner, chartered management accountant, and former international M&A advisor who has built and sold his own businesses. He helps middle-market owners grow, build a business that runs without them, and prepare for an exit on their own terms. Part consultant, part peer who has been in your shoes. To map where your business depends on you and plan the way out, get in touch.